Two remote job offers land in your inbox. One pays $90,000 as a W-2 employee. The other pays $100,000 as a 1099 contractor. The second one looks better, right?
Not always. The paycheck number is only half the story. Taxes, health insurance, paid time off, and retirement matching can swing the real result by thousands of dollars a year. Let’s work through it with actual 2026 numbers.
Disclaimer: This article is for general education, not personal tax advice. Check your numbers with a CPA or the IRS before making big decisions.
The Core Difference in One Paragraph
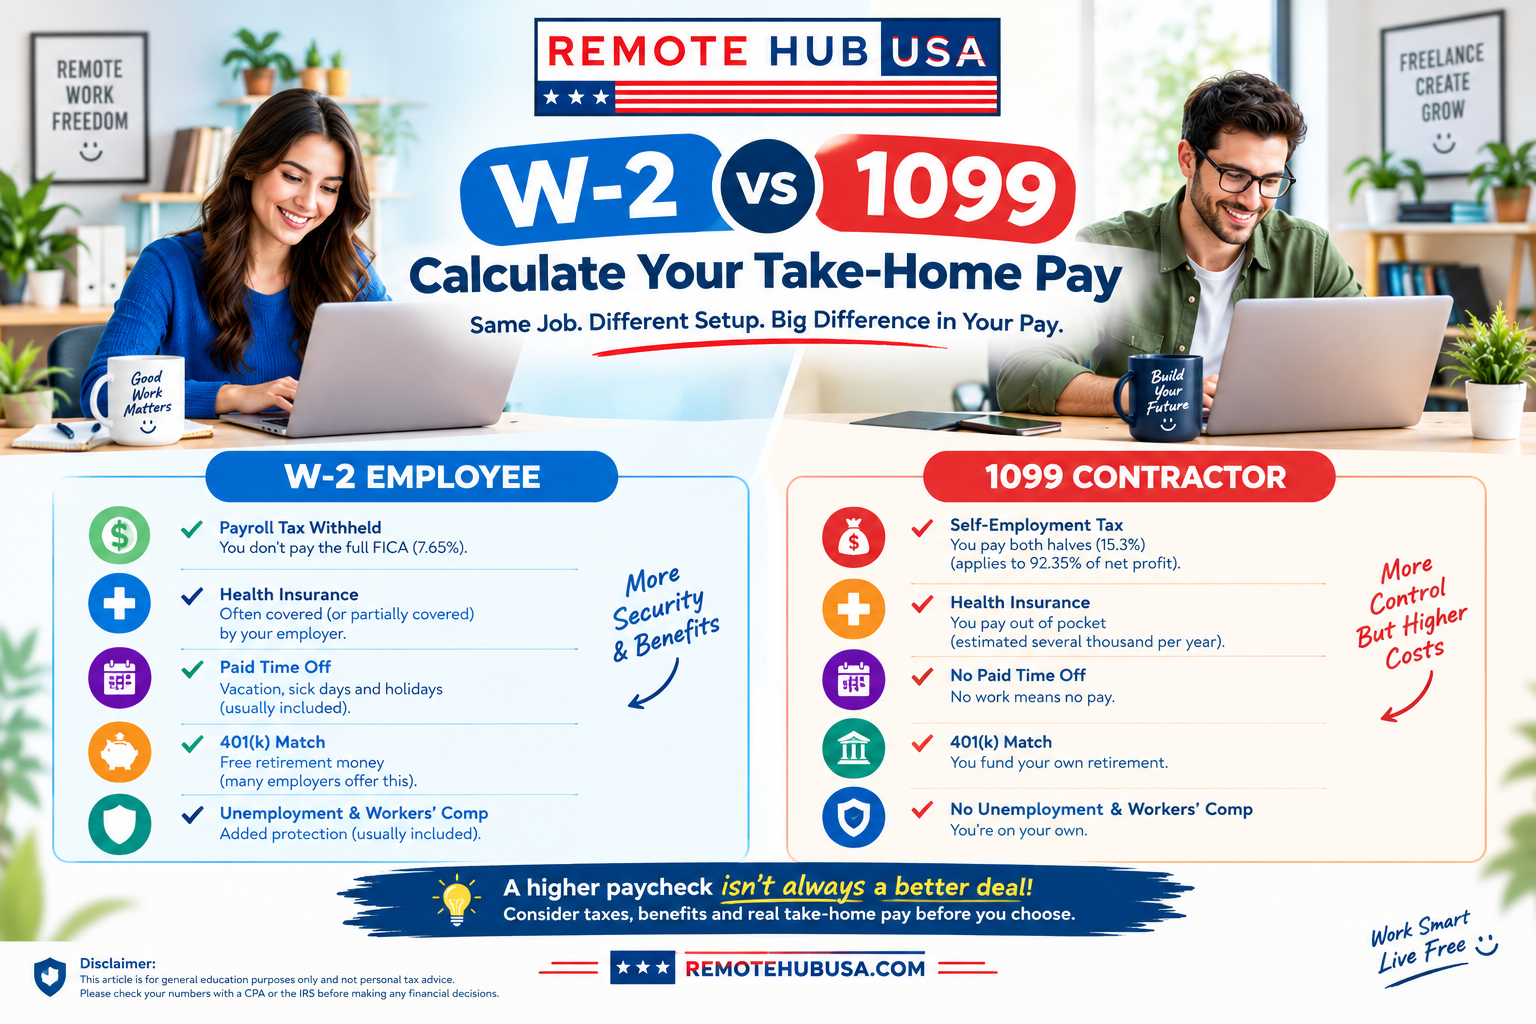
As a W-2 employee, your employer withholds taxes and pays half of your Social Security and Medicare (FICA) tax. As a 1099 contractor, you’re self-employed. You pay both halves yourself, no one withholds anything, and you send the IRS money every quarter.
2026 IRS Tax Numbers You Need to Know
Before comparing job offers, here are the official 2026 federal tax figures that determine what you actually keep:
Standard deduction: $16,100 (single), $32,200 (married filing jointly)
Federal tax brackets (single): 10% up to $12,400, 12% up to $50,400, 22% up to $105,700, 24% up to $201,775
Social Security tax: 12.4% on self-employment income up to $184,500
Medicare tax: 2.9% with no cap, plus 0.9% extra on income above $200,000 (single)
Self-employment (SE) tax: 15.3% total, applied to 92.35% of your net profit
QBI deduction: Many 1099 earners can deduct up to 20% of qualified business income, which softens the tax hit
Example 1: Same $90,000 Salary, Two Different Job Types
Let’s look at a single filer living in a state with no state income tax and taking no extra deductions.
| Pay & Tax Breakdown | W-2 Employee | 1099 Contractor |
| Gross Pay | $90,000 | $90,000 |
| Payroll / Self-Employment Tax | $6,885 | $12,717 |
| Federal Income Tax | $10,970 | $6,599 |
| Take-Home Pay (Before State Tax) | $72,145 | $70,684 |
Two things stand out here:
The contractor pays almost double in payroll tax ($12,717 vs. $6,885).
However, the QBI deduction cuts the contractor’s federal income tax significantly, so the pure tax gap is smaller than most people expect—around $1,461 in this scenario.
The bigger gap isn’t in taxes at all. It’s in what the W-2 job gives you for free.
What a W-2 Remote Job Quietly Pays For
When you’re a 1099 independent contractor, you have to replace all of these benefits out of your own pocket:
Employer’s half of FICA: About $6,885 on a $90K salary.
Health insurance: Employer plans often cover a large share of premiums. Buying your own plan on the marketplace can run several thousand dollars a year, depending on your age, state, and coverage level.
Paid time off (PTO) and holidays: As a contractor, no work means no pay.
401(k) match: Free retirement money that many W-2 employers offer.
Unemployment insurance and workers’ comp: Contractors usually have neither protection.
This is the exact part freelancers forget when they get excited about a higher hourly rate or annual contract number.
Example 2: Is $100K on a 1099 Really Better Than a $90K W-2?
Now let’s compare that tempting $100,000 contractor offer against a $90,000 W-2 remote salary once health insurance enters the picture.
| Compensation Factor | W-2 at $90K | 1099 at $100K |
| Take-Home (Before State Tax) | $72,145 | $77,635 |
| Estimated Health Insurance You Pay | $0 (Employer shares cost) | Around –$8,000 |
| True Take-Home After Insurance | ~$72,145 | ~$69,635 |
Even with a $10,000 higher headline number, the 1099 contractor can easily end up behind by over $2,500 once health insurance is counted—and that’s before factoring in unpaid vacation days and zero retirement matching. Your own insurance cost will differ, so be sure to plug in your real quote.
A Rule of Thumb That Works: A 1099 remote job offer should usually pay 25% to 35% more than a comparable W-2 salary just to come out even.
How to Calculate Your Own 1099 Take-Home Pay (Step-by-Step)
Want to run the numbers on a contract offer you just received? Follow these 8 steps:
Start with net profit: Gross income minus legitimate business expenses.
Calculate taxable SE income: Multiply your net profit by
0.9235. Multiply that result by15.3%to get your Self-Employment (SE) tax.Claim the SE adjustment: Deduct half of your SE tax from your gross income.
Subtract the standard deduction: Subtract $16,100 if filing single in 2026 ($32,200 if married filing jointly).
Apply the QBI deduction: Deduct up to 20% if you qualify. (Note: Some service professions, such as consultants and lawyers, lose this benefit at higher income thresholds).
Calculate federal income tax: Apply the 2026 federal tax brackets to your remaining taxable income.
Factor in state taxes: Add your state income tax, if your state has one.
Find your net pay: Subtract your total tax bill (SE tax + federal tax + state tax) from your net profit. That’s your real take-home pay.
Skip the manual math: Instead of building a spreadsheet, plug your numbers directly into our free Freelancer Calculator or compare W-2 paychecks using our USA Salary Calculator to get your instant take-home breakdown.
Tax Deductions That Help 1099 Remote Workers
Self-employed remote workers have more legal tax-saving tools than they realize. Keep clean receipts and records for:
Home office deduction: A dedicated space in your home used regularly and exclusively for work.
Internet and phone bills: The business-use percentage of your monthly bills.
Hardware and software: Laptops, monitors, ergonomic chairs, and essential software subscriptions.
Self-employed health insurance premiums: Often 100% deductible above the line.
Retirement contributions: Funding a Solo 401(k) or SEP IRA, which can reduce your taxable income significantly.
Professional fees: Industry courses, accounting software, CPA fees, and business subscriptions.
Real-world tip: Open a separate business bank account on day one. Mixing personal and business money is the fastest way to get confused—and overpay—when tax season arrives.
Quarterly Estimated Taxes: Don’t Skip Them
W-2 employees get taxes taken out of every paycheck automatically. As a 1099 contractor, you must pay the IRS four times during the year on these exact deadlines:
April 15
June 15
September 15
January 15 (of the following year)
If you miss these deadlines, expect an IRS underpayment penalty. To stay safe in the “safe harbor,” many freelancers pay at least 100% of last year’s total tax (110% if your adjusted gross income was above $150,000) or 90% of this year’s expected tax.
A simple habit works best: move 25% to 30% of every client payment into a separate high-yield savings account the moment you get paid.
Remote Work and State Taxes
Remote workers often overlook state tax rules until it’s too late. Your state income tax depends on where you live, and sometimes where your employer is headquartered or where you physically perform the work.
No-Income-Tax States: If you live in Texas, Florida, Washington, Nevada, Tennessee, Wyoming, South Dakota, or Alaska, your take-home pay improves immediately.
High-Tax States: If you live in California or New York, state income tax can take a serious bite out of both W-2 and 1099 earnings.
Always run the numbers with your specific state included before accepting an offer.
Is Your “1099 Contractor” Job Actually a W-2 Job?
Some companies misclassify workers as 1099 contractors simply to avoid paying payroll taxes and benefits. The IRS looks closely at how much behavioral and financial control the company has over your work:
Do they dictate your exact daily hours?
Do they require specific tools and direct supervision?
Is it long-term, exclusive work where you cannot take on other clients?
If your “1099 job” looks and feels like regular employment, you may be misclassified. You can file Form SS-8 with the IRS to request an official worker status determination.
So, Which One Should You Choose?
Choose a W-2 remote job if: You value predictable paychecks, employer-sponsored health benefits, paid vacation, simpler taxes, or have a family relying on your medical coverage. (Applying for W-2 roles? Make sure your resume passes automated filters with our free ATS Resume Checker).
Choose a 1099 remote contract if: You want schedule flexibility, can negotiate a 25%–35% higher rate, work with multiple clients across different regions (use our Ultimate Time Zone Converter to manage client calls), and are disciplined about saving for quarterly taxes.
Frequently Asked Questions (FAQ)
Is a 1099 job better than W-2 for taxes?
Not automatically. As a 1099 worker, you pay more in payroll tax (15.3% self-employment tax), though you can claim business write-offs and potentially the 20% QBI deduction. The better option depends on your income bracket, business expenses, and healthcare needs.
How much should I set aside for taxes as a 1099 worker?
A safe starting point is 25% to 30% of your net income. Adjust that percentage up or down based on your total household income and your state’s tax rate.
Do 1099 workers pay more tax than W-2 employees?
Usually yes, because 1099 contractors pay both the employer and employee halves of Social Security and Medicare taxes. However, legitimate business deductions and the QBI deduction can offset a large part of that difference.
What is the self-employment tax rate in 2026?
The self-employment tax rate in 2026 is 15.3%, broken down as 12.4% for Social Security (on net self-employment income up to $184,500) plus 2.9% for Medicare (with no income cap).
Can I switch from 1099 to W-2 later?
Yes. Many freelancers transition into full-time W-2 employee roles with their favorite clients, and many W-2 employees go freelance after building an emergency savings fund and a steady client base.
Final Thoughts
Never compare remote job offers by the headline salary number alone. Always compare your true take-home pay after federal taxes, self-employment taxes, health insurance, and lost benefits.
Before you sign your next contract, run both scenarios using our free Freelancer Tax Calculator and USA Salary Calculator, then subtract your health insurance quote and state tax. Ten minutes of math right now can easily save you thousands of dollars this year.